Who does what
What’s Automated. What a Person Owns.
Written back · July
“Capitalise equipment over $2,500. Expense the rest.”
One line in the policy, applied to every purchase since.
✦ Automated
✦
Every close already confirmed, every decision already written back
✦
Your written policies remembered as rules the close is checked against
A licensed CPA owns
—
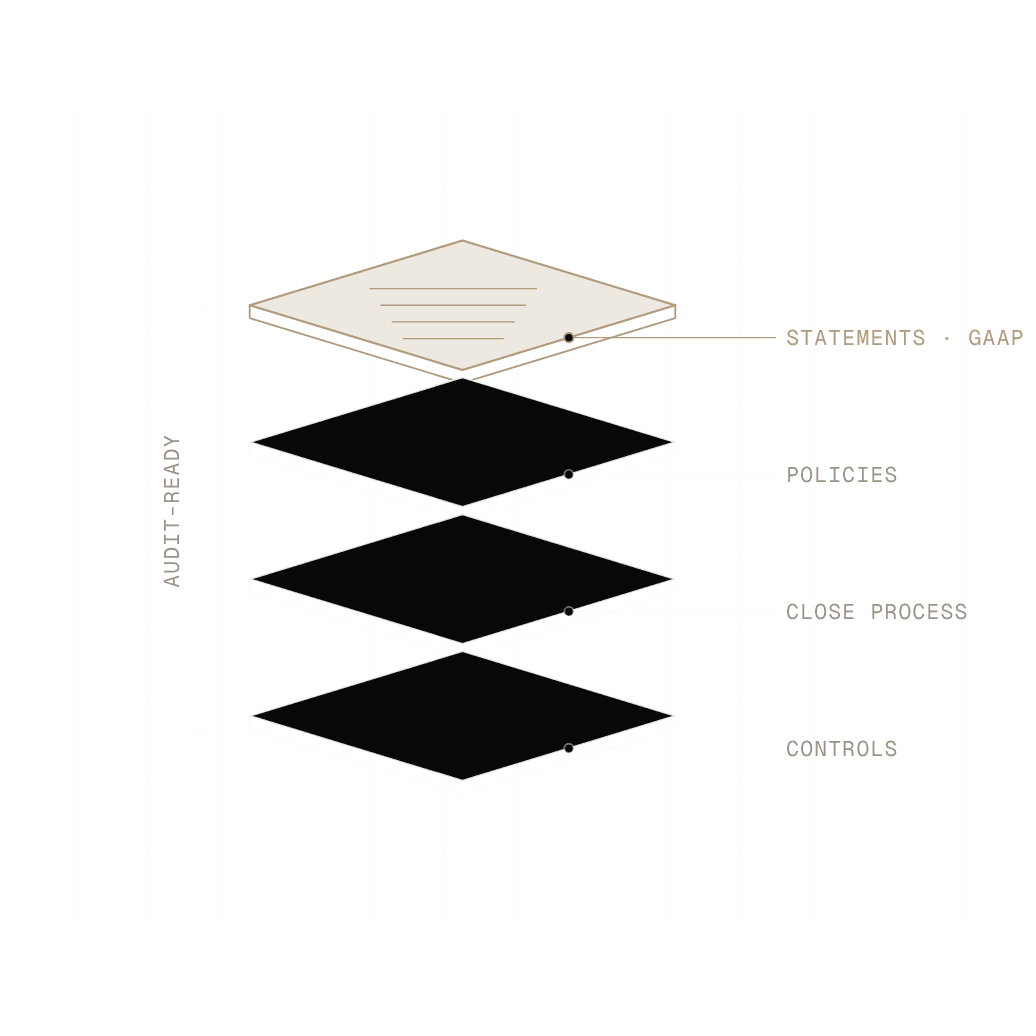
Preparing GAAP-ready statements
—
Writing your accounting policies
—
Designing the close process and controls with you
—
The schedules an auditor asks for
What’s included
Statements an Outsider Can Rely On
01
GAAP-ready financial statements, prepared for a first audit, a lender or due diligence
02
Accounting policies written down: revenue, capitalisation thresholds, accruals, so every close makes the same call
03
A close process designed for you: the calendar, the checklist, and who approves what
04
A chart of accounts built for the reporting you will need next year, not just this month
05
Internal controls sized for your stage: approvals, segregation of duties, who can move money
06
Audit preparation: the schedules and support an auditor asks for, ready before they ask
How it works
01
We look at where you are
The books, the policies you have (written or not), and what is coming: an audit, a round, a sale.
02
We close the gaps
Adjustments booked, policies written, schedules built, with a CPA working through each one.
03
The process keeps it there
The policies and the close process carry into every close after, so the next audit starts from books already in shape.
FAQ
Questions
How is this different from the monthly close?
Do you perform the audit?
When should we start?